Key Points
- Three Dividend Kings, Target, Hormel, and Procter and Gamble, appear undervalued after setbacks, offering potential for market-beating total returns.
- Target's stock trades near a four-year high following improved traffic and comps, with analyst price targets trending upward toward the mid-$180s.
- Hormel and Procter and Gamble both show depressed valuations alongside signs of stabilization, including heavy institutional buying and improving retail market share.
Dividend Kings are not always a good buy. While they are always good to hold, cyclicality can boost valuations and depress yields, setting the stage for poor returns long-term. The trick is finding these stocks when they’re down or, even better, in the midst of rebounding.
Dividend Kings in this position provide attractive valuations and yields that can produce market-beating total returns over time. Total returns matter most for retirement accounts because they truly measure wealth building, including capital appreciation and dividend income. In this scenario, savvy investors use those dividends to compound their positions and accelerate annual returns.
Target Is in the Midst of a Structural Recovery
Target’s (NYSE: TGT) dividend-increase history spans more than 50 years, and it is positioned to continue annual increases given its financial health, cash flow, and business growth outlook.
The 2026 narrative is that Target is recovering from structural missteps that drove shoppers away; now they’re coming back, and it is reflected in the results. The Q2 results revealed a second consecutive quarter of growth, with outperformance underpinned by improved traffic. Comps grew 3.8% on the 3.6% traffic increase, prompting management to raise guidance. Guidance isn’t robust but aligns with recovery and is likely to be cautious, given the traffic return.
Analyst trends are central to the stock's recovery, as they reflect the turnaround. The Q2 report triggered numerous revisions, including upgrades and price target increases, strengthening sentiment and pushing the stock's rating toward the high end of the price target range. MarketBeat tracks 32 analysts with current ratings on TGT, with 56% of ratings at Hold and 35% at Buy. The consensus target offers little upside as of mid-September, but the trend is what counts, with consensus up versus last year, last quarter, and last month, and high-end targets leading to the mid-$180s.
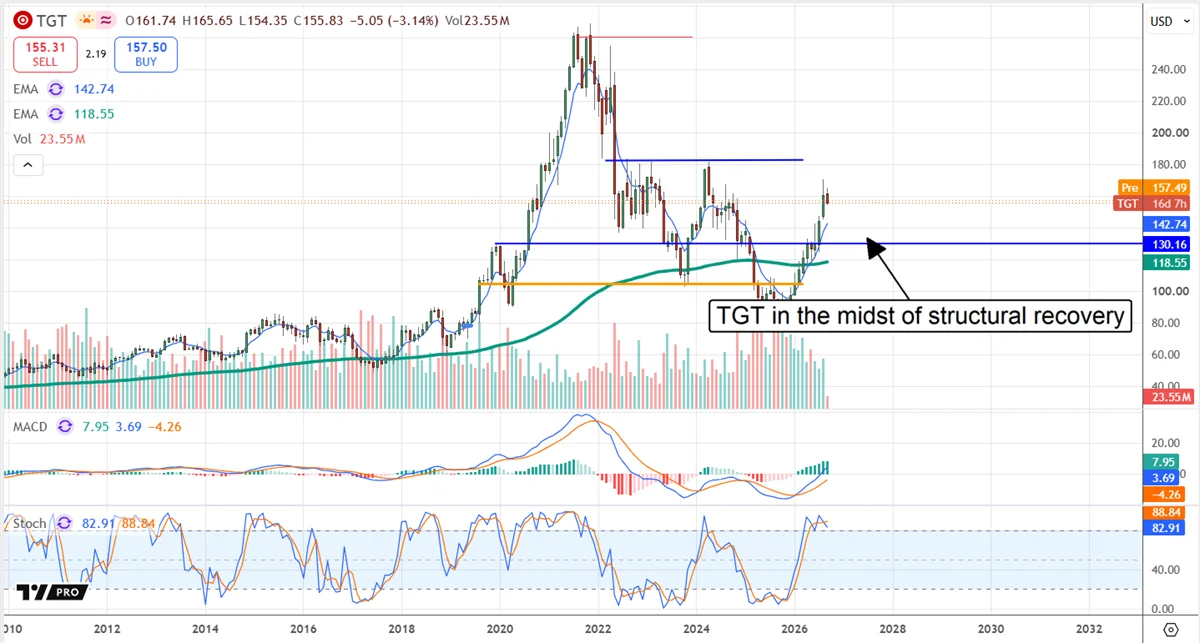
The mid-$180s puts TGT stock at a four-year high, above a critical pivot point. In this scenario, Target’s market is on track for a full price recovery and may reclaim the all-time high of $260 within the next few years. The dividend yields approximately 3% at recent prices.
Hormel Stock Trades Below Its Decade Low
Hormel (NYSE: HRL) faces headwinds, including consumer habits, costs, and margins. Weak results and guidance cuts depressed the stock to a decade low, pushing its valuation into the low end of the historic range and its dividend yield into the high. The dividend, yielding more than 5.5%, is reliable, as the company is a Dividend King with a management team committed to capital return.
Reported earnings and trailing-12-month payout ratios make the dividend look barely covered; however, cash flow is sufficient to fund operations while returning capital. The pace of increases is likely to be slow in the coming years, but the high yield and potential share-price gains offset it.
Hormel is more than 50% off its highs, 10% below the analysts’ low-end target, and sitting on solid support. Support dates back to a 2013 continuation signal and is highlighted by increased volume.
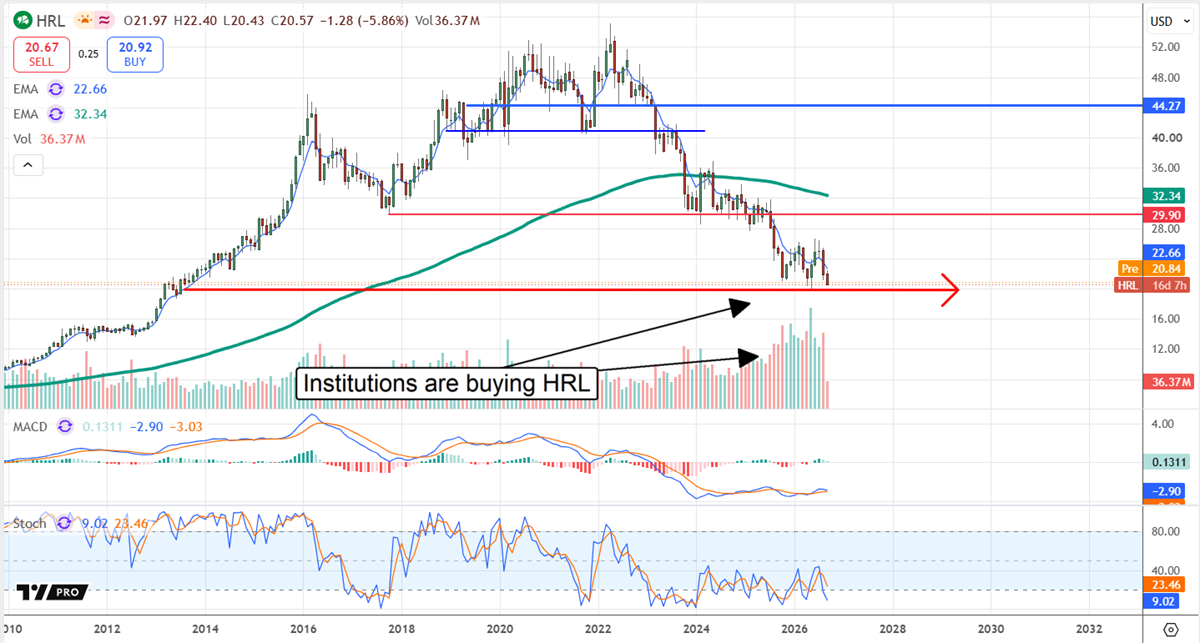
Institutions, including the Hormel Foundation, own more than 90% of the stock and have been accumulating over the past few quarters. They, specifically the Hormel Foundation, which uses its dividends for philanthropic work, help to ensure the company remains focused on its long-term, capital-returning goals.
Procter & Gamble on Track for Structural Market Share Recovery
Procter & Gamble shares are down on weak results, margin pressure, consumer headwinds, and valuation concerns, but those factors are not what investors should focus on today. Today, Procter & Gamble shares trade at a depressed valuation, offer a reliable dividend yield of 3%, and are poised for a quiet reacceleration in market share and growth.
Management highlighted an interesting detail during a recent earning conference call and a later investor event: among P&G's largest U.S. retail customers, the share that are holding or gaining market share climbed from under 10% in the first half of the fiscal year to around 50% in the second. That improvement points to renewed momentum in P&G's biggest and most profitable market. In this environment, the company has two levers for growth: its own efforts and those of its retail customers.
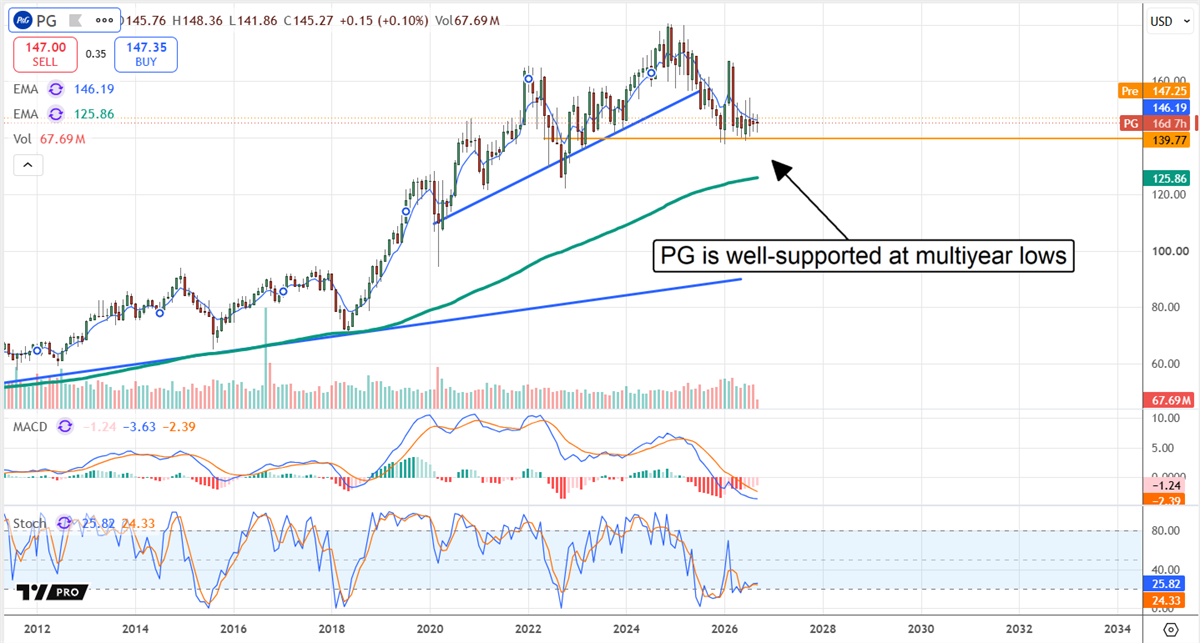
Analysts show conviction in this play, with 24 rating it a consensus of Moderate Buy and a 54% Buy-side bias within the data. The group has been trimming price targets in 2026, but still provide a floor for price action, with the low-end target at $145. The $145 target aligns with the stock's bottom action and is unlikely to be broken. Institutions are gobbling up shares.
Get Income-Generating Stocks Like Target in Your Inbox.
Stop riding the roller coaster of the stock market and sign-up to receive DividendStocks.com's daily ex-dividend stocks and dividend investing news for TGT and related companies.
Companies Mentioned in This Article:| Company | Current Price | Price Change | Dividend Yield | P/E Ratio | Consensus Rating | Consensus Price Target |
|---|
| Target (TGT) | $158.90 | +2.0% | 2.92% | 16.50 | Hold | $159.52 |
| Hormel Foods (HRL) | $20.96 | +1.9% | 5.58% | 33.26 | Hold | $26.14 |
| Procter & Gamble (PG) | $146.08 | +0.6% | 2.98% | 22.07 | Moderate Buy | $161.19 |
About Thomas Hughes
Experience
Thomas Hughes has been a contributing author for DividendStocks.com since 2019.
- Professional Background: Thomas Hughes is the Managing Partner of Passive Market Intelligence LLC, a market research platform he launched in 2023 with the mission: “We watch the market so you don't have to.” He has worked as a blogger, stock market commentator, and independent analyst since 2010 and has been actively involved in trading and investing since 2005.
- Credentials: He holds an Associate of Arts in Culinary Technology—training that honed his discipline, attention to detail, and ability to anticipate outcomes, all of which carry over into his work as a market analyst.
- Finance Experience: Thomas has been writing about finance and investing since 2011, when he discovered it could be more than a personal passion—it could be a profession. He’s been a contributing writer for DividendStocks.com since 2019.
- Writing Focus: He specializes in the S&P 500, small-cap stocks, dividend and high-yield strategies, consumer staples, retail, technology, oil, and cryptocurrencies. His analysis blends chart-based technical setups with key fundamental insights, helping readers identify actionable trends.
- Investment Approach: Thomas takes a hybrid approach that combines technical analysis with deep fundamental research. He often writes about macroeconomic shifts, earnings trends, and sentiment-based trading signals.
- Inspiration: Thomas first became interested in stocks after attending a seminar on how to buy and sell your own shares. That event opened his eyes to the market's potential and sparked a lifelong interest in investing.
- Fun Fact: Thomas took up model railroading by accident a few years ago—and now he can’t stop running the rails.
- Areas of Expertise: Technical and fundamental analysis, S&P 500, retail and consumer sectors, dividends, market trends
Education
Associate of Arts in Culinary Technology